Online pokies with PayID in Australia: who takes it, who pays it back, and where the transfer really breaks
 Available in US
Almost every pokies site aimed at Australians takes PayID now. Deposits land in seconds, the bank charges nothing, and you never type a card number. That part is genuinely good.
The part that gets glossed over: PayID mostly runs one direction. You can put money in through the New Payments Platform at nearly any site on this page, but sending winnings back out to your PayID is a capability only a handful of cashiers actually have. Everywhere else, you deposit by PayID and then cash out by bank transfer, crypto, or whatever else the operator’s processor can manage. Sites do not advertise this distinction on the deposit page. You find out at withdrawal time.
The second thing nobody flags: an NPP transfer cannot be recalled. No chargeback, no dispute form, no card issuer to escalate to. Visa gives you a fighting chance if a merchant turns hostile. PayID gives you a receipt. That changes which sites are worth the risk, and it is the reason this page spends as much space on the payment rail as on the operators using it.
And there is a third failure point most readers hit before they ever reach a cashier: their own bank. If you hold a Commonwealth Bank or a classic ANZ personal account, your default daily PayID limit is A$1,000, and your first transfer to a new payee can sit for up to 24 hours. Your deposit did not fail because the site is dodgy. It failed because of a setting in your banking app that nobody told you about.
The short version: PayID deposits work at effectively every offshore pokies site serving Australia and clear in under a minute for free. PayID withdrawals are the rare part — SkyCrown and Lucky7 are the reliable two-way names. Minimum deposit sits at A$10 at the low end. Nothing here holds an Australian licence, because no such licence exists.
Which online pokies sites accept PayID in Australia?
Twelve sites carry genuine PayID cashiers for Australian players in 2026: SkyCrown, Lucky7, Ricky Casino, Neospin, Joe Fortune, Aussie Play, Stay Casino, Rolling Slots, 7Bit Casino, Wild Tokyo, Stellar Spins and thepokies.net. All are offshore — Curaçao or Tobique licensed. SkyCrown and Lucky7 support PayID withdrawals as well as deposits.
How A PayID Deposit At A Pokies Site Actually Works
PayID is not a payment company. It is an addressing layer sitting on top of the New Payments Platform, the real-time rail Australian Payments Plus launched in February 2018. Instead of keying a BSB and account number, you point money at an email address, a mobile number, or an ABN. Osko, the service most banks label these transfers with, runs on the same infrastructure. So does PayTo. Same plumbing, different badges.
The scale matters for why casinos bothered integrating it. NPP connects more than 100 banks, credit unions, mutuals and fintechs, shifts roughly A$7 billion a day, and handles close to two billion real-time payments a year. Every major bank is on it — CommBank, ANZ, NAB, Westpac, plus ninety-odd smaller institutions. When POLi shut down on 30 September 2023 with no successor, PayID inherited most of the Australian casino deposit traffic by default. There was nothing else left that was instant, free, and bank-native.
Setting Up Your PayID
One-time job, done inside your banking app, takes about three minutes. You nominate either your mobile number or your email address and link it to a specific account. Find it under PayID in the CommBank app, ANZ’s app settings, or the equivalent screen at NAB and Westpac. Once registered, that identifier is yours across the whole NPP network.
A detail worth getting right before you go near a cashier: register the PayID to the account you actually intend to fund from, and make sure the account name on it matches the name on your casino registration. Mismatched names are a real rejection cause, not a theoretical one. If your bank says Jonathan and the site says Jonny, the transfer can be held or bounced on a name-check.
Making The Deposit
Open the cashier, pick PayID, and the site returns two things: a PayID to send to, and a unique payment reference. Both matter. The reference is how the processor maps an anonymous incoming bank transfer to your specific account balance — drop it and your money arrives somewhere real but unattributed, and recovering it means a support ticket and a wait.
Then you leave the casino entirely, open your banking app, and send the payment like any other transfer. Funds normally show up in the casino balance within ten to sixty seconds. Some cashiers take five to thirty minutes because their processor batches confirmations rather than listening to the NPP webhook live. Neither the bank nor the site charges a fee on this. Actually free, for once, rather than “free” in the promotional sense.
Why It Clears When A Card Doesn’t
Here is the mechanism, and it explains nearly everything about PayID’s popularity for this particular use case.
Card payments carry a four-digit merchant category code. Gambling merchants get MCC 7995 — betting, casino gaming chips, lottery tickets, off-track wagering. That code travels with the authorisation request, so your bank sees “casino” in milliseconds and can decline before the transaction reaches the operator. It is the reason the same card buys coffee without incident and then dies at a pokies cashier.
NPP transfers carry no merchant code at all. There is nothing structural in the message for a bank to pattern-match against. So banks screen these payments differently: by the receiving account name, by the payment reference, and against internal lists of accounts already identified as belonging to gambling processors. A transfer that looks like an ordinary person-to-person payment tends to go through. A transfer to an account the bank has already flagged does not.
That is also why PayID reliability wobbles month to month at the same site. Offshore operators rotate payment processors and receiving accounts constantly. A fresh account clears for a week or three, then a bank recognises it and adds it to the list, and suddenly the deposit that worked in March fails in June. Nothing changed at your end. The processor got burned.
Depositing From Your Phone
Because PayID is addressed by mobile number and the transfer happens inside a banking app, this is a phone-first rail by construction. Every site here runs either a mobile browser build or a progressive web app rather than a native download, since app stores will not distribute real-money pokies to Australian users. You will be switching between two apps — casino and bank — which on a phone is two taps rather than the desktop dance of copying a reference between browser tabs.
What is the minimum PayID deposit at a pokies site?
A$10 is the realistic floor, offered at Ricky Casino and Neospin among others. Some cashiers advertise A$20. Claims of A$2 or A$5 minimums appear in marketing copy but rarely survive contact with an actual cashier. Budget A$10 as the working minimum and treat anything lower as unconfirmed.
Which Pokies Sites Take PayID — And Which Let You Cash Out With It
Twelve sites are worth naming. They are ordered by how well they handle PayID specifically, not by bonus size — a A$10,000 headline figure is worth nothing if the cashier cannot send your winnings back down the rail you deposited with.
Before the breakdowns, the one structural fact that determines this whole ranking. Inbound PayID is easy: the processor publishes a receiving PayID and waits. Outbound PayID is hard, because the processor needs an Australian bank account capable of initiating NPP credits to arbitrary third-party payees, held under a banking relationship that tolerates gambling flow. Very few payment service providers clear that bar. That is the entire explanation for why “deposit only” is the default and two-way PayID is the exception. Competitors report the pattern; the cause is the useful part.
| Site | PayID direction | Min deposit | Licence | Distinguishing feature |
|---|---|---|---|---|
| SkyCrown | Deposit + withdraw | A$20 | Curaçao | Genuine outbound PayID in the cashier |
| Lucky7 | Deposit + withdraw | A$20 | Tobique | ~35 min tested PayID cashout, 168 providers |
| Ricky Casino | Deposit + withdraw | A$10 | Curaçao | Longest AU tenure at the A$10 floor |
| Neospin | Deposit + withdraw | A$10 | Curaçao | AUD-native accounts, lowest entry point |
| Joe Fortune | Deposit + withdraw | A$20 | Curaçao eGaming | Operating since 2016, RTG-led AU lobby |
| Aussie Play | Deposit + withdraw | A$20 | Curaçao | Native AUD, RTG-exclusive catalogue |
| Stay Casino | Deposit + withdraw | A$20 | Curaçao | Reload cadence for repeat depositors |
| Rolling Slots | Deposit + withdraw | A$20 | Tobique | 15,000+ games, PayID filed under Bank Transfer |
| 7Bit Casino | Deposit + withdraw | A$20 | Curaçao | Crypto-native, PayID in / crypto out |
| Wild Tokyo | Deposit only | A$20 | Curaçao | 8,000+ games, USDT ~11 min for cashout |
| Stellar Spins | Deposit (withdraw unconfirmed) | A$20 | Curaçao family | Newer entrant, limited payout record |
| thepokies.net | Deposit (withdraw unconfirmed) | A$10 | Offshore | Rotating numbered mirror domains |
Minimum deposits marked A$20 are the common cashier default where the site does not publish a lower PayID-specific floor. Where a figure could not be confirmed against the cashier itself, it is not stated as fact below.
SkyCrown — PayID Both Ways
SkyCrown holds a Curaçao licence and runs a pokies-led lobby with crypto sitting alongside fiat in the cashier. The welcome package is advertised around A$4,000 plus 400 free spins across staged deposits. What earns it the top slot has nothing to do with that figure: SkyCrown is one of the few AU-facing cashiers where PayID genuinely works in both directions. You deposit by PayID and you withdraw by PayID, to the same identifier, without being rerouted to a three-day bank wire.
For a reader whose entire question is “can I get my money back out the way I put it in,” that makes SkyCrown the default starting point. One caveat needs stating plainly, because no competitor states it: outbound PayID depends on SkyCrown’s processor relationship, and those relationships lapse. A site listed as two-way today can quietly become deposit-only after a processor change, with no announcement. Check the cashier’s withdrawal screen before you deposit, not after you have won something.
Lucky7 — Fastest Tested PayID Cashout
Licensed by the Tobique Gaming Commission, Lucky7 runs roughly 6,000 games from 168 separate providers — Nolimit City, BGaming, Hacksaw Gaming, Pragmatic Play, Play’n GO, Yggdrasil and Big Time Gaming all appear in the same lobby. That provider count is the highest here by a wide margin, and the filtering actually works, which matters more than the raw number. Welcome offer runs A$3,000 plus 200 free spins on a 35× bonus-only wagering model.
Two details make it interesting for PayID specifically. Independent testing puts its PayID cashout around 35 minutes, the fastest recorded on any site of this library size. And the KYC threshold sits at A$1,000 cumulative, meaning smaller sessions complete without a document upload at all. The bonus-only wagering is also the cleaner arrangement — 35× applies to the bonus alone, not to bonus plus deposit, which roughly halves the turnover figure compared with sites that combine both and hope you do not read closely.
Ricky Casino — The Long-Tenure Benchmark
One of the oldest brands still actively marketed to Australian players, Curaçao licensed, with AUD-native accounts and something over 3,000 pokies weighted towards Pragmatic Play, Betsoft and BGaming. Live dealer tables are present. Payouts land around the 24-hour mark. The A$10 minimum deposit is the lowest among the established names, and its PayID cashier has been in place for years rather than months — which, on a rail where processor churn is the main failure mode, counts for more than a slick landing page.
The trade-off is the bonus fine print. That advertised A$7,500 welcome figure is a staged total spread across a long sequence of deposits, and the wagering attached runs high — in the 35× to 50× range depending on which tier you claim. Treat Ricky Casino as the reliability benchmark and ignore the headline number. If you want a site where the deposit rail has a track record and A$10 gets you in the door, this is it. If you want a bonus you can realistically clear, look at the wagering column first and adjust your expectations downward.
Neospin — Lowest Realistic Entry Point
Curaçao licensed, AUD-native, positioned squarely at the low-deposit end of the market. The A$10 PayID floor is confirmed across multiple independent Australian review sources, and because accounts are denominated in Australian dollars there is no conversion spread quietly shaving your balance on the way in and out.
The advertised welcome package runs to around A$11,000, which sounds absurd and is: it is a staged aggregate across a long run of deposits, not a match on your first one. Read it as a marketing ceiling rather than an offer. What Neospin is genuinely good for is the reader depositing A$10 or A$20 at a time who wants those amounts to arrive intact and be counted in the currency they earn in. For that specific profile — small, frequent, AUD — it is the cleanest option on this page.
Joe Fortune — Running Since 2016
Nine years of continuous operation serving Australian players, which on this list is close to geological. Joe Fortune holds a Curaçao eGaming licence issued through the Curaçao Gaming Control Board framework — the same regulatory family as Ricky Casino, Hellspin, Croco and Lucky Green — and accounts are AUD-native. The catalogue runs to roughly 500 games built around RealTime Gaming, plus table games and a live dealer studio. Welcome offers commonly sit at 120% plus 25 free spins, with larger staged packages promoted during campaigns.
Its lobby is the pub-pokies aesthetic rather than a generic European casino skin, which is a genuine preference split rather than a quality judgement: RTG titles feel closer to what an Australian player recognises from a venue floor. The practically useful detail is that Joe Fortune accepts Neosurf alongside PayID. When your bank blocks the NPP transfer — and at some point it will — having a cash voucher route already sitting in the same cashier saves you hunting for an alternative site mid-session.
Aussie Play — Native AUD, RTG Only
Curaçao licensed, Australian-themed, with native AUD accounts and no conversion step anywhere in the flow. The advertised welcome package reaches A$7,500 across staged deposits. Banking covers PayID plus Bitcoin, Ethereum and USDT, and its bank wire withdrawal has been tested at around 42 minutes — quick for a fiat rail.
The catalogue is RealTime Gaming exclusively. That is a narrower library than anything else here, and whether it counts against the site depends entirely on what you play. If you want Nolimit City’s brutal volatility or Hacksaw’s newer releases, this is the wrong address. If you specifically like RTG’s Australian-themed pokies and have no interest in a 15,000-title catalogue you will never work through, the narrowness stops being a flaw and starts being a filter.
Stay Casino — Built For Repeat Deposits
Curaçao licensed, mid-tier, with a promotional model weighted towards reloads and recurring drops rather than a single vast welcome figure. The staged welcome package runs to around A$3,500 and payouts are reported around 24 hours. Standard multi-provider pokies library, PayID in the cashier.
There is a mechanical reason this suits the reader depositing repeatedly rather than once: after your first PayID transfer to the site’s payee clears, the first-payee hold your bank applies is done with. Subsequent transfers to that same identifier go through immediately. A site built around weekly reloads and a bank rail that gets faster after the first use are a reasonable match. Public detail on this brand is thinner than on Ricky Casino or Joe Fortune, so the honest position is that its payout record is less documented, not that it is worse.
Rolling Slots — PayID Hiding Under Bank Transfer
Tobique-family licence, and the largest raw catalogue on this page at over 15,000 games. The welcome offer is the biggest headline here too — 310% up to A$6,400 plus 570 free spins, on a 30× bonus-only model. Solana withdrawals have been recorded around 10 minutes and PayID around 15.
The quirk worth knowing before you conclude PayID is unavailable: Rolling Slots does not put a PayID button in its cashier. The route sits under Bank Transfer, and you find the PayID option after selecting that. Readers regularly decide the site does not support PayID and leave. It does. On the catalogue, apply the obvious discount — quality thins noticeably past the first few thousand titles, and a 15,000-game library is a search-and-filter problem as much as a selling point.
7Bit Casino — Deposit Fiat, Withdraw Crypto
A long-established crypto-first casino, Curaçao licensed, that added Australian fiat rails including PayID rather than the other way round. The headline welcome total reaches A$10,800 plus 250 free spins, spread across several deposits — an aggregate, as always. Strong Megaways representation in the catalogue.
Its value here is as a template rather than a ranking. 7Bit’s architecture was built around crypto from the start, so depositing by PayID and cashing out in USDT or Bitcoin is the native path rather than a workaround. That combination sidesteps the outbound-NPP bottleneck entirely: you get the convenience of a bank-app deposit and the speed of a crypto withdrawal, without needing your operator’s processor to hold an Australian account capable of paying you back. If you already hold crypto, this is arguably the most sensible structure on the page.
Wild Tokyo — Deposit Only, And That Matters
Curaçao licensed, 8,000-plus games, a neon-soaked lobby, and a welcome package of 250% up to A$5,300 with 600 free spins at 45× wagering. Gates of Olympus, Reactoonz 2 and Sun of Egypt 2 head the pokies selection. On games and bonus size it would rank far higher than tenth.
It sits here because of the thing this page exists to flag. Wild Tokyo takes PayID for deposits and does not reliably return money down the same rail. A PayID withdrawal was recorded at 1 hour 48 minutes through CommBank back in March 2026, but that is history rather than the current advertised route — USDT, tested around 11 minutes, is what the cashier steers you toward now. Deposit here by PayID and you are committing to cashing out by crypto. That is fine if you have a wallet. It is a nasty surprise if you assumed the rail ran both ways and only checked at withdrawal time with a balance sitting there.
Stellar Spins — Newer, Thinner Record
A more recent arrival in the Curaçao family, pokies-led, with PayID present in the cashier and a staged welcome package in line with the rest of the market. It appears here because Australian players search for it by name, which is a fact worth respecting rather than ignoring.
What it does not have is history. Independent payout documentation is sparse compared with Joe Fortune’s nine years or Ricky Casino’s track record, and there is no meaningful body of evidence about how it behaves when a withdrawal gets complicated. On a payment rail where transfers cannot be reversed, operating tenure is not a nice-to-have — it is most of what you have to go on. A new site with a generous bonus and no payout record is a bet on the operator as well as on the pokies. Size the first deposit accordingly.
thepokies.net — The Mirror-Domain Problem
Substantial branded search demand, and the reason needs explaining properly. thepokies.net operates through a long sequence of numbered mirror domains — the base address attracts ISP blocking under ACMA’s enforcement powers, so the operator keeps standing up successors with numeric suffixes. That is a rational response to being blocked. It also creates the single most dangerous situation on this entire topic.
Here is the problem. A reader searching the brand name lands on whichever mirror ranks that week, sees a familiar-looking lobby, and sends an irreversible PayID transfer to whatever receiving identifier that page displays. There is no way to verify from the page itself whether it belongs to the operator or to somebody who cloned the layout and swapped the PayID. Card fraud has a chargeback path. NPP transfers do not. Per-mirror payout performance is not independently verifiable either, so nothing useful can be said about how any particular domain behaves. If you use this site, reach it from a link you already trust rather than a search result, and keep the deposit small enough that being wrong is survivable.
Can you withdraw pokies winnings straight back to PayID?
At a minority of sites, yes. SkyCrown and Lucky7 support genuine outbound PayID, with Lucky7 tested around 35 minutes. Most cashiers accept PayID deposits but route withdrawals through bank transfer or crypto, because outbound NPP requires the processor to hold an Australian account able to credit arbitrary payees.
Why PayID Deposits Fail, And Whose Fault It Usually Isn’t
Most guides on this subject treat a failed deposit as the casino’s problem. Four times out of five it is not. The failure happens inside your own bank, for reasons that have nothing to do with the site you are trying to fund, and the error message you get back will not tell you which one fired.
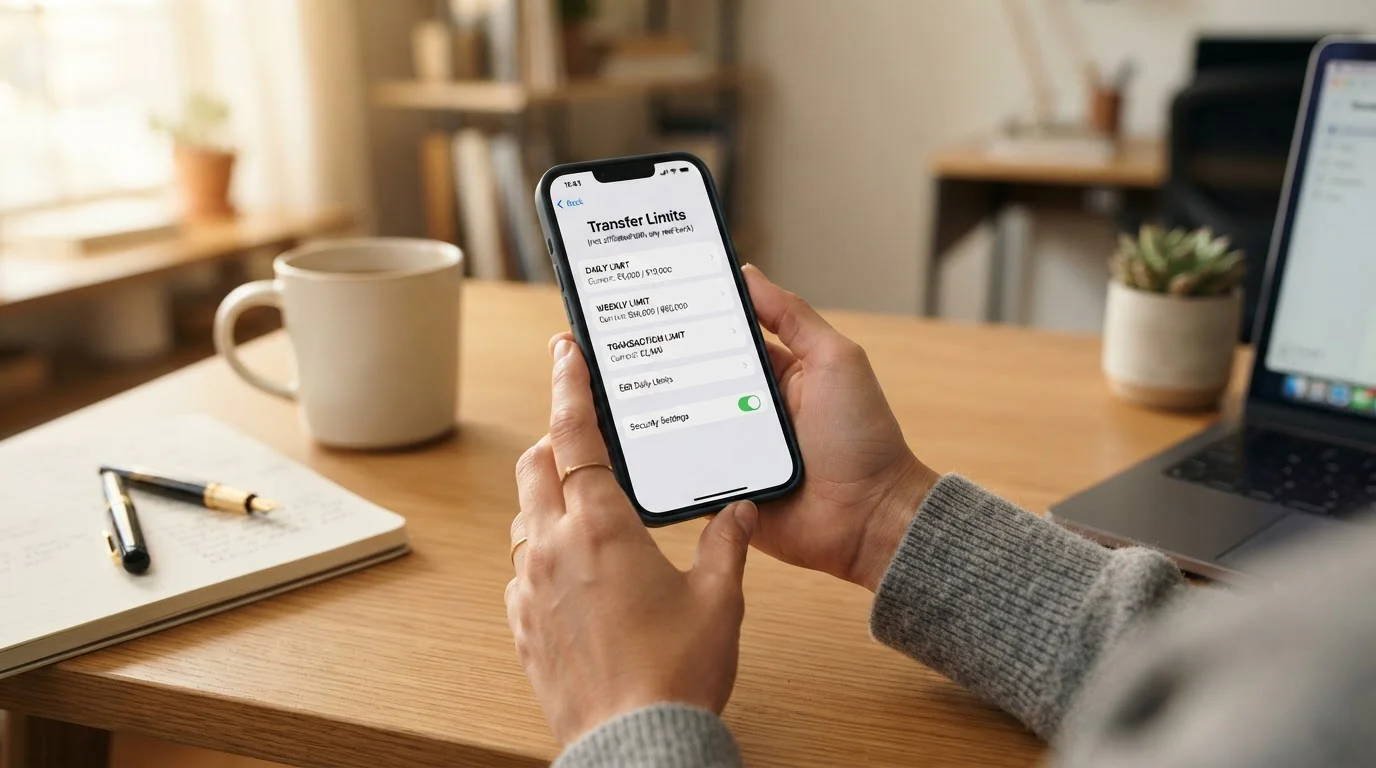
Your effective deposit limit at any given moment is not the number in your banking app, and it is not the maximum on the casino’s banking page. It is the smallest of three separate ceilings stacked on top of each other.
Layer one is your bank’s default daily PayID limit. It applies to every NPP transfer out of your account in a rolling 24-hour window, regardless of destination. Layer two is a gambling sub-cap, which some banks apply on top of the default to transactions their monitoring classifies as gambling-bound. Layer three is the casino’s payment processor, which runs its own per-transaction and per-day caps entirely independently of your bank — typically A$2,000 to A$5,000 per transaction at the operators here.
Your real limit is the minimum of those three. Every ceiling above the minimum is irrelevant to the deposit in front of you. Work out which layer fired and you know which lever to pull; skip that step and you end up blaming the casino for a setting in your own app.
Your Bank’s Daily Cap
The numbers below were verified against each bank’s own published help documentation. They are the single most useful thing on this page, because five of these eleven banks default to a ceiling below what a meaningful casino deposit requires.
| Bank | Default daily PayID cap | First-payee hold | Where to raise it | Gambling sub-cap |
|---|---|---|---|---|
| Commonwealth Bank | A$1,000 | Up to 24 hours | NetBank → Settings → Transfer & BPAY limits | A$5,000/day opt-in toggle |
| NAB | A$1,000–3,000 by account | Generally instant | NAB Internet Banking → Settings → Daily Limits | None on PayID; card-only block |
| ANZ (classic) | A$1,000 | Up to 24 hours, Voice ID above A$1,000 | ANZ App → Settings → Daily transfer limits | A$5,000/day opt-in |
| ANZ Plus | A$5,000 | None | ANZ Plus App → Settings → Daily limits | None |
| Westpac | A$2,000 (A$1,000 legacy accounts) | High-value first payments may hold | Online Banking → Service & Security → Daily Payment Limit | A$5,000/day soft cap |
| Macquarie | A$3,000 with Authenticator, A$2,000 without | Generally instant | Macquarie App → Profile → Settings → Limits | None |
| ING Orange Everyday | A$5,000 | ~12 hours on first payee | Not raisable — hard NPP ceiling | None |
| UBank | A$5,000 | Generally instant | UBank App → Settings | None |
| Bendigo Bank | A$2,500 | Variable | Internet Banking, phone for higher | None |
| BankSA | A$2,000 | Westpac group policy | Internet Banking → Service → Daily Limit | Inherits Westpac A$5,000 |
| Bank of Melbourne | A$2,000 | Westpac group policy | Bank of Melbourne Internet Banking | Inherits Westpac A$5,000 |
Read the first column again if you bank with CommBank, classic ANZ, Westpac, BankSA or Bank of Melbourne. A$1,000 to A$2,000 a day is your starting ceiling, and it is below what several cashiers ask for a first deposit that qualifies for the full welcome tier. Your deposit attempt is statistically likely to fail on the bank side before the casino ever sees it.
Two rows deserve flagging. ING’s A$5,000 is structural rather than a setting — it cannot be raised by phone, branch visit or written request, so ING is comfortable up to A$5,000 a day and a brick wall above it. And Macquarie’s figure assumes the Authenticator app is enabled; without it your effective ceiling drops, which makes Authenticator setup effectively compulsory if you plan to use Macquarie for this at all.
The First-Payee Hold
Not a cap. A delay, applied to the first transfer you ever send to a new PayID payee, designed to slow down scam payments. CommBank holds first payments to a new payee for up to 24 hours by default. Classic ANZ does the same and adds Voice ID verification above A$1,000. ING has been reported holding around 12 hours. ANZ Plus, NAB, UBank and Macquarie generally transmit immediately.
The consequence is specific and catches people out constantly: your first deposit at a new site can sit in limbo for a day while you conclude the casino has swallowed it. It has not. Once that first payment clears, every subsequent transfer to the same payee goes through instantly. If you are testing a new site, send a small first transfer well before you actually want to play, and let the hold expire on its own time.
Gambling Sub-Caps
Separate from the default, narrower, and invisible until you exceed it. Westpac applies a A$5,000-a-day soft cap on outbound PayID transfers its monitoring classifies as gambling-bound, and BankSA and Bank of Melbourne inherit it as Westpac group brands. CommBank’s app exposes a gambling toggle that throttles casino-bound PayID to A$5,000 a day or blocks it outright depending on configuration. ANZ runs a comparable A$5,000 opt-in.
NAB is the odd one out, and worth noting for a reason that cuts against its own marketing. NAB’s gambling block is built on debit-card merchant codes, which means it does not cover PayID at all. A customer who switches on NAB’s gambling block believing they have shut off their casino spending has shut off their cards and left the NPP rail wide open. If you are using a bank block as a self-control measure, test it with a small transfer rather than trusting the label.
None of this screening is legally mandated, incidentally. No Australian bank is required to block an offshore pokies deposit and none is required to allow one. Each sets its own posture, changes it without notice, and applies it inconsistently across payment types. That discretion, not any single rule, is what players actually collide with — and it is why building your deposit plan around one bank is fragile.
Name Mismatches
Short section, because the fix is short. If the account name attached to your PayID does not match the name on your casino account, the transfer can be held or rejected on a name-check. Register both under the same legal name. Nicknames, middle-name variations and abbreviations all cause this.
When The Casino’s Processor Is The Problem
Layer three. Every offshore operator routes PayID through a payment service provider that holds the Australian-side identity on its behalf — Picksellpay, Volt, Hayvn, Triple-A, Nodapay, MiFinity and Pay4Fun all appear in this market. Those processors run their own per-deposit ceilings, commonly A$2,000 to A$5,000 per transaction, with daily limits between A$5,000 and A$20,000. These are not the operator’s advertised maximum deposit. They are risk controls applied transaction by transaction, and they sit entirely outside your bank’s view.
Processor churn is also why a site’s PayID status is not a permanent attribute. When an operator switches processors, the receiving identifier changes, the caps change, and the outbound capability can appear or vanish. A site listed as two-way six months ago may be deposit-only now. Check the cashier, not an old review.
Worked example, because the model is only useful applied. A CommBank customer tries to deposit A$2,500. Layer one fires first at A$1,000 and the transfer is declined with a limit message that does not say which limit. The gambling sub-cap at A$5,000 never triggers. The processor cap at around A$3,000 never triggers either. The diagnosis is layer one, and the fix is raising the NetBank daily transfer limit — not switching sites, not contacting the casino.
Second example. A Westpac customer wants A$6,000 in. They raise their layer-one default from A$2,000 to A$10,000 using SecurID in advance, which handles the first ceiling. But the A$5,000 gambling soft cap is active on the account, so layer two now binds at A$5,000 regardless of the raise. The processor caps each individual transaction at roughly A$3,000. Net result: A$3,000 plus A$2,000 goes through, the final A$1,000 fails until tomorrow’s window resets or the sub-cap is disabled in the app. Three ceilings, three different numbers, one useless error message.
Why did my PayID deposit to a pokies site fail?
Usually your bank, not the site. Check three things in order: your daily PayID limit (A$1,000 default at CommBank and classic ANZ), whether a first-payee hold of up to 24 hours is running, and whether a gambling sub-cap is active. Name mismatches between bank and casino accounts also cause rejections.
Withdrawals: What The Timings Really Look Like
The rail is fast. The operator is not. Confusing the two is the reason readers get angry at NPP for delays that are entirely the casino’s doing.
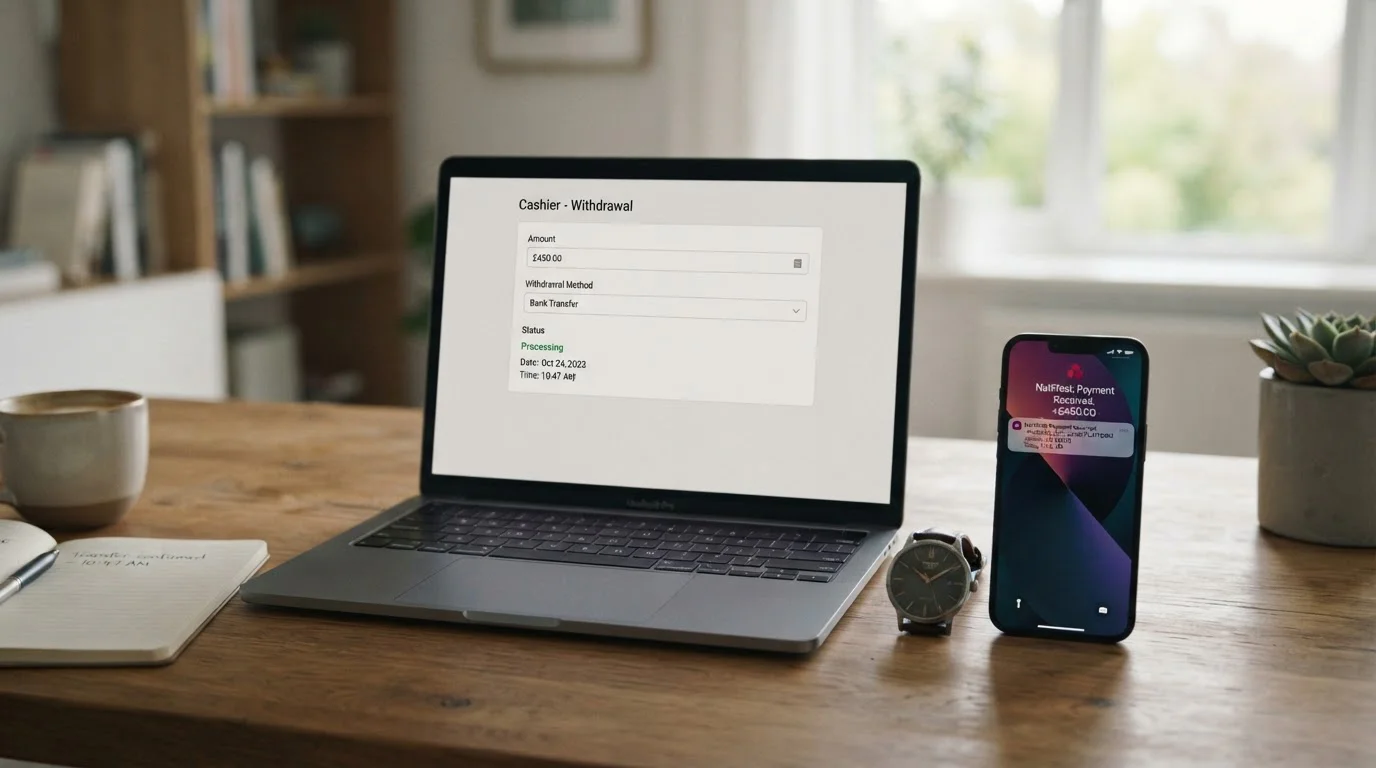
An NPP credit, once initiated, settles in seconds. Every published PayID withdrawal figure at the sites above — 28 minutes, 35 minutes, an hour and 48 minutes — is almost entirely operator processing time with a few seconds of actual transfer at the end. The variable you are choosing between when you pick a site is not transfer speed. It is how long a human or an automated system at the operator takes to approve the request and hand it to the processor.
The First Withdrawal Is The Slow One
Expect 12 to 48 hours on your first cashout at any site here, regardless of what the marketing says about instant payouts. Those instant figures describe the second withdrawal onward. The first one carries identity verification, and that queue runs on the operator’s timetable.
This is the single most common complaint about offshore pokies sites, and most of it is a misunderstanding rather than misconduct. A site advertising 35-minute PayID cashouts is not lying; it is quoting the steady state and letting you discover the first-time delay yourself. Plan for the first withdrawal to take a day.
KYC And When It Triggers
Know Your Customer checks usually fire at first withdrawal rather than first deposit, which is a deliberate design choice — friction at the cashier costs deposits, friction at withdrawal does not. Lucky7 publishes a A$1,000 cumulative threshold, below which documents are not requested at all. Several other sites operate comparable thresholds without publishing them.
What gets asked for: photo identification, proof of address, and sometimes a screenshot of the account you deposited from. Have these ready before you need them. The practical trap is depositing by PayID from one account, then requesting withdrawal to a different identifier — that mismatch triggers manual review and turns a 35-minute cashout into a three-day conversation with support.
Where The Time Actually Goes
Break a two-hour PayID withdrawal into its parts and the shape becomes obvious. Request submitted, then a queue wait for operator approval, which is where the bulk of the time sits. Then handoff to the processor, which has its own batch schedule. Then the NPP credit, which takes seconds. Then your bank crediting the funds, which is instant unless it decides to review the incoming payment.
Crypto shortens this by removing the processor’s Australian banking dependency, not by being intrinsically faster. USDT at around 11 minutes and Solana at around 10 beat PayID’s best recorded times for exactly that reason, which is why crypto-native sites like 7Bit push you toward it. Bank transfer fallback, at one to three business days, is slower because it drops off the real-time rail entirely and back into overnight batch processing.
How long does a PayID pokies withdrawal actually take?
Around 30 minutes to two hours at sites with genuine outbound PayID, once your account is verified. The first withdrawal takes 12 to 48 hours because identity checks run then. Nearly all of that time is operator approval queue — the NPP transfer itself completes in seconds.
The Legal Position, Stated Plainly
No site on this page holds an Australian licence. Not one. That is not an oversight on their part or a gap in the research — it is because no such licence exists and none can be issued.
What The Interactive Gambling Act 2001 Actually Prohibits
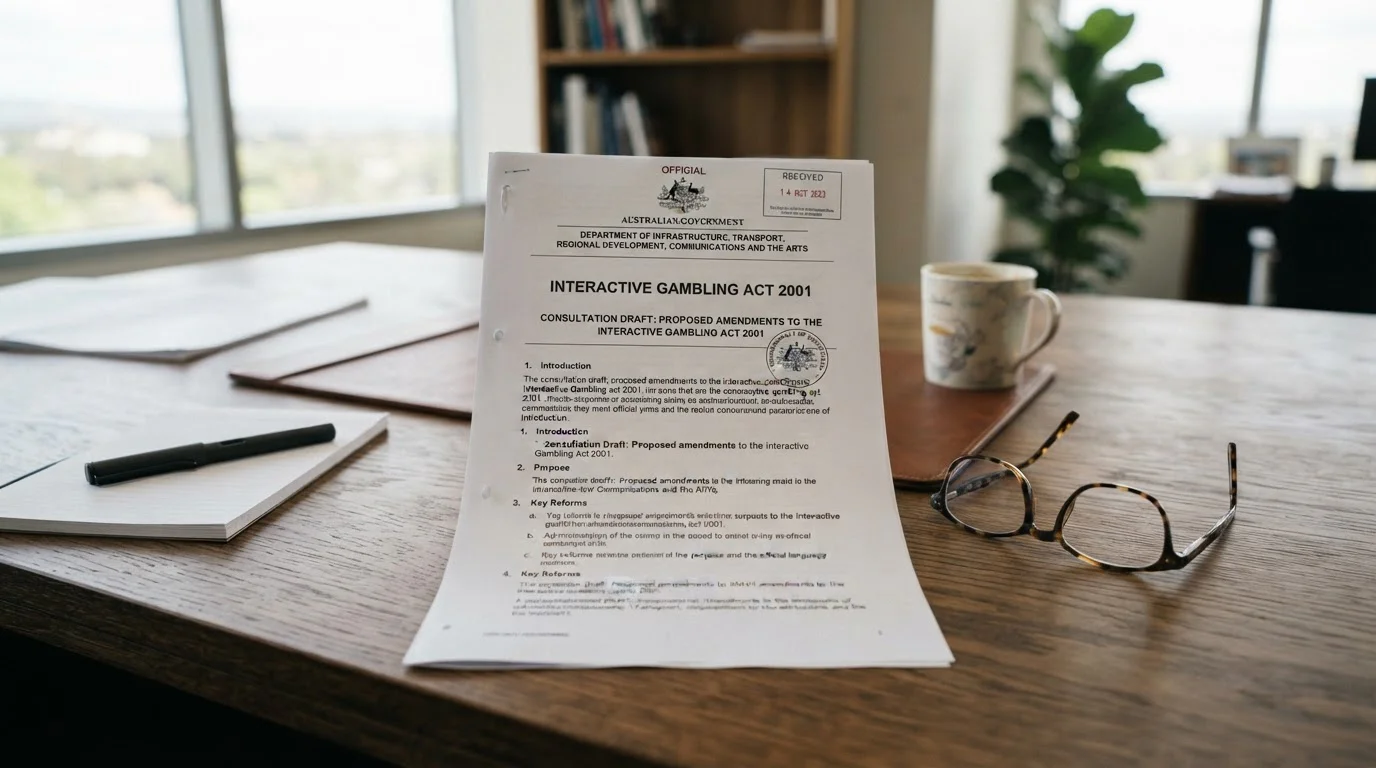
The Interactive Gambling Act 2001 makes it illegal to supply online casino-style games to a person physically in Australia. Pokies and slot machines are named explicitly, alongside roulette, blackjack and poker. The Australian Communications and Media Authority administers it, with policy sitting inside the Department of Infrastructure, Transport, Regional Development, Communications and the Arts. Banned services also must not be advertised in Australia.
The detail that matters to you: the prohibition binds the operator, not the player. There is no offence in the Act for an Australian individual who plays at an offshore pokies site. The legal exposure sits with the company supplying the service, which is precisely why those companies are all incorporated somewhere else — Curaçao mostly, with Tobique, Anjouan and Costa Rica filling out the rest.
ACMA’s enforcement toolkit runs through infrastructure rather than prosecution. It can direct internet service providers to block access to illegal gambling websites, supported by an industry code, and it can refer directors and principals of offending companies to the Australian Border Force. Since the 2017 amendments, more than 220 online gambling services have withdrawn from the Australian market. The site-blocking power is also the direct cause of the mirror-domain behaviour discussed earlier — block the address and the operator stands up a numbered successor.
What Changed In 2026
Parliament passed the Interactive Gambling Amendment (Gambling Reform) Bill 2026 on 19 August 2026. Most of its provisions commence on 1 January 2027, and the package is substantial: restrictions on gambling advertising across television, radio, online and sports venues; a global opt-out register for gambling ads; limits on direct marketing of inducements to new account holders during their first 14 days, to people who deregistered from BetStop within the previous three months, and to any customer identified as at risk of gambling harm; strengthened BetStop operation; measures aimed at harmful online lottery products; and expanded ACMA enforcement including the power to order takedowns of both advertisements and illegal services themselves.
One clause in that list deserves attention from anyone reading ranked casino lists, including this one.
> a ban on commissions to staff or affiliates based on customer activity — Australian Communications and Media Authority, summary of the Interactive Gambling Amendment (Gambling Reform) Bill 2026
Every page competing for this topic is an affiliate page, paid on customer activity. From January 2027 that compensation model faces a statutory ban. Not one of the sites currently ranking for PayID pokies mentions this, which is itself informative about how those rankings are assembled. Separate legislation also lets ACMA recover its costs for administering BetStop, the inducement rules and the opt-out register.
Why Your Licensed Bookmaker Has No Pokies
ACMA publishes a register of Australian-licensed interactive wagering providers. Sportsbet, TAB, Ladbrokes, Neds and Bet365’s Australian arm are on it, they are genuinely licensed here, and several accept PayID happily. They also have no pokies lobby, and cannot have one.
Wagering — betting on sport and racing outcomes — is licensed and lawful onshore. Casino-style gaming is prohibited by the same Act that permits the wagering. So a locally licensed operator accepting your PayID deposit is a real thing that exists; it simply cannot sell you the product you came for. That is the gap offshore sites occupy, and understanding it explains why the choice on this topic is never “licensed Australian pokies versus offshore pokies.” There is no first option.
It also means BetStop, the national self-exclusion register, does not reach any site on this page. BetStop covers Australian-licensed wagering services. Registering with it excludes you from Sportsbet and TAB, and does precisely nothing about Ricky Casino. If you are using self-exclusion as a harm-reduction tool, that gap is worth knowing about before you rely on it.
What Offshore Licensing Does And Doesn’t Give You
A Curaçao or Tobique licence is not decoration, but it is not consumer protection in any sense an Australian would recognise. It means a regulator exists, the operator pays for authorisation, and there is a nominal complaints channel. What it does not mean: enforceable recourse from Australia, a compensation scheme if the operator fails, deposit segregation you can verify, or any authority that will compel payment of a disputed withdrawal.
Compare the two sides of the transaction honestly. Your bank is regulated by APRA and ASIC and will answer a complaint. The company on the other end of your PayID transfer answers to an authority in the Caribbean, and your realistic leverage in a dispute is a support ticket and a public review. That asymmetry is the actual risk on this topic, and it is why an operator’s years in business matter more than the size of its welcome bonus.
Is playing online pokies with PayID legal in Australia?
The Interactive Gambling Act 2001 prohibits operators from offering online pokies to Australians, but creates no offence for the player. No Australian pokies licence exists, so every site here is offshore. ACMA blocks these sites rather than prosecuting users. The legal risk sits with operators; your risk is commercial.
The Part About Irreversibility Nobody Advertises
PayID gets sold on safety. You never expose card details, the transfer is bank-to-bank, it uses infrastructure your own institution built. All true, and all of it obscures the trade you are making.
No Chargeback, No Dispute Path
An NPP transfer clears and settles in real time and cannot be recalled. There is no chargeback mechanism, no dispute form, no card issuer with an obligation to investigate on your behalf. Once the money leaves, the only route back is the recipient voluntarily sending it.
Now set that against the card you were told to avoid. A Visa or Mastercard deposit carries dispute rights. If an operator refuses a legitimate withdrawal, voids a balance on a spurious terms breach, or simply stops responding, a card gives you a chargeback claim with a regulated process behind it. PayID gives you a transaction receipt and a phone number for the casino’s support desk.
So the honest framing is this: PayID protects your card data and removes your recourse. Competitors publish the first half of that sentence and stop. For small, frequent deposits at a site with years of payout history, the trade is reasonable. For a large deposit at a site that launched last quarter, you are wiring unrecoverable funds to a company answerable to nobody you can reach. The rail is not the risk. The counterparty is, and the rail is what removes your protection from the counterparty.
Mirror Domains And Lookalike Sites
ACMA’s blocking power guarantees that offshore operators rotate domains. That is a legitimate operator behaviour with an illegitimate side effect: readers become accustomed to the brand they want living at a slightly different address each time they look, which trains exactly the habit that scams exploit.
Clone a casino’s front end, register a near-identical domain, buy some search traffic, and swap the receiving PayID in the cashier. The visitor sees a familiar lobby and a deposit screen, sends an irreversible bank transfer, and has no counterparty at all. Nothing on the page distinguishes the real mirror from the fake one, because the real mirror is also a new domain with no history. Reach these sites through a link you already hold rather than a fresh search result, and keep first deposits small.
The Facebook And App-Based “Pokies” Pattern
There is persistent Australian search demand for pokies on Facebook and for app platforms like VPower, usually attached to promises of free credit. These are not casinos. There is no cashier, no licence in any jurisdiction, and no corporate entity. They run on individual agents who sell credits and settle by direct bank transfer, which in practice means you send PayID to a stranger’s personal account and hope they load your balance.
The “free credit” on offer here deserves its quotation marks. No operation of any size hands out withdrawable money to strangers, and an agent-run credit reseller is the last place it would come from. Casinos are not charities, licensed ones least of all, and unlicensed ones are not even pretending. Combine an irreversible payment rail with an anonymous counterparty and no regulator and you have assembled the worst possible configuration available on this topic. If a Facebook group is your deposit method, the pokies are not the risk.
Are PayID pokies deposits safe, and can a transfer be reversed?
The transfer itself is bank-grade secure and exposes no card details. But NPP payments are irreversible — no chargeback, no dispute process, unlike cards. That makes the operator’s track record the thing that matters. Small deposits at long-established sites; nothing substantial at brand-new ones.
When PayID Isn’t An Option: The Alternatives Compared
Sometimes the transfer will not go through, or the site takes PayID inbound only and you need a cashout route. The useful way to rank the alternatives is by distance from your bank, because bank proximity is what determines whether a payment gets screened at all.
| Method | Deposit speed | Withdrawal | Fees | Visibility to your bank |
|---|---|---|---|---|
| PayID (NPP) | 10 seconds to 30 minutes | At a minority of sites | Nil both sides | Partial — no merchant code, but payee is screened |
| Crypto (BTC, USDT, ETH) | Instant to 30 minutes | 10 minutes to 1 hour | Network fee, exchange spread | Bank sees a transfer to an exchange only |
| Neosurf voucher | Instant | None — deposit only | Voucher purchase fee | None — cash purchase in store |
| Bank transfer | 1 to 24 hours | 1 to 3 business days | Usually nil | Full — screened on payee and reference |
| BPAY | 1 to 2 business days | Rare | Usually nil | Full — screened on biller |
| Debit or credit card | Instant when it works | 3 to 5 business days | Possible cash advance fee | Complete — MCC 7995 travels with it |
Neosurf
A cash voucher bought over the counter at a newsagent or convenience store. You pay cash, receive a code, and enter the code at the cashier. Your bank is not involved at any point, which makes it the one rail that cannot be blocked, throttled or screened — there is nothing for the bank to see.
The catch is absolute: deposit only, no exceptions. Neosurf cannot pay you out, so it is a funding workaround paired with some other withdrawal method. Joe Fortune keeps it alongside PayID in the same cashier, which is the sensible arrangement — a backup already in place for the week your bank decides NPP transfers to that payee are no longer acceptable.
Crypto
Bitcoin, Ethereum, USDT and increasingly Solana. Your bank sees a transfer to a registered exchange, which is an ordinary and entirely legal transaction, and never sees the casino at all. That structural distance is why crypto is the most reliable rail here rather than the fastest.
It also solves the outbound problem cleanly. Since the operator’s processor does not need an Australian banking relationship to pay you in USDT, crypto withdrawals routinely beat PayID’s best times — 10 to 30 minutes at the sites above. The cost is setup friction: exchange account, identity verification, wallet, plus exposure to the spread on the way in and out. If you already hold crypto, the deposit-by-PayID and cash-out-by-crypto pattern that 7Bit is built around is arguably the best structure available. If you do not, expect an afternoon of admin before your first deposit.
Bank Transfer And BPAY
The slow, fully visible options. A standard bank transfer runs one to 24 hours inbound and one to three business days out, because it drops off the real-time rail and into overnight batch processing. BPAY is slower still and rarely offered for withdrawals. Both are screened by your bank on the receiving account or biller, exactly as PayID is, without PayID’s speed advantage to compensate.
They are worth knowing about for one reason: bank transfer is the fallback route most deposit-only sites use to pay you. When Wild Tokyo or Rolling Slots cannot send PayID outbound, this is generally what you get instead unless you take crypto.
Cards
Instant when they work, and frequently they do not. MCC 7995 travels with every card authorisation, so your bank can decline in milliseconds, and the 2024 restrictions on credit card use for gambling narrowed things further. Withdrawals take three to five business days where supported at all, and some cashiers will not return funds to a card.
Cards retain one genuine advantage nothing else here offers: chargeback rights. If recourse against a dodgy operator matters more to you than speed, a card is the only rail on this list that gives you any.
What can you use instead if a site only accepts PayID for deposits?
Crypto is the usual answer — USDT or Bitcoin cash out in 10 to 30 minutes and need no Australian banking relationship from the operator’s processor. Bank transfer works but takes one to three business days. Neosurf funds deposits only and cannot pay you out at all.
Minimum Deposits And Low-Stakes Play
A$10 is the practical floor at Ricky Casino and Neospin. That number sounds low, and it is — until you run the arithmetic on what it actually buys you.
What A$10 Actually Buys You
Assume a typical Megaways pokie at A$0.20 a spin. A$10 gives you 50 spins, base game, no bonus. Pair that with a 100% match — now you have A$20 — and the 35× bonus-only wagering requirement common at these sites means you need to turn over A$350 (35 times the A$10 bonus) before you can withdraw a cent. At A$0.20 a spin that is 1,750 spins. The A$10 deposit funds 50. You are short by 1,700 spins worth of turnover, which at the same stake is another A$340 of your own money through the machine.
The match is not free credit. It is a multiplier on the volume of play the site expects from you in exchange for letting you keep anything. The A$10 minimum gets your account open, not through the wagering requirement. To clear a bonus attached to a A$10 deposit at realistic stakes requires either absurd luck or several top-ups, and if you are topping up repeatedly you were never playing at the minimum — you were playing at the cumulative total.
Why Sub-A$10 Claims Don’t Hold Up
A$2 and A$5 minimums appear in marketing copy and occasionally in the pool of search terms, but asking a cashier for those figures produces a different number. When the advertised floor contradicts the actual cashier’s working minimum, the cashier wins. Budget A$10 as the real entry point and treat anything cheaper as unconfirmed until you see it in your own banking app.
Bonuses, “Free Credit” And The No-Deposit Question
Every staged welcome package on this page is an aggregate across multiple deposits, not a match on your first one. A$7,500, A$10,800, A$11,000 — those are ceilings you approach by depositing repeatedly over weeks, with different percentage matches and wagering models at each tier. Treat them as the operator’s maximum possible marketing claim rather than an offer you will collect in one session.
How Wagering Requirements Work
A 35× bonus-only requirement means you must turn over 35 times the bonus amount before a withdrawal is permitted. If you claim A$100 bonus, you owe A$3,500 in total bets. At a A$0.50 spin that is 7,000 spins. Wins along the way count toward turnover but do not reduce the requirement — land a A$20 win and you still owe the same 7,000 spins, just with a slightly larger balance to do it with.
Bonus-only models are cleaner than deposit-plus-bonus, because the latter applies the multiplier to both parts. A 40× requirement on a A$100 deposit plus A$100 bonus is 40 times A$200, which is A$8,000 turnover instead of A$4,000. Always check which model applies and do the arithmetic before you claim, because completing the playthrough is the only route to cashing out anything at all.
The cynical read, which is also the accurate one: wagering requirements exist to ensure most players never complete them. The bonus increases your starting balance, which extends your session, which gives the house edge more spins to work with. That is not a conspiracy theory. It is the business model stated plainly.
What No-Deposit Offers Really Are
Occasionally a cashier will credit a small balance — A$10, A$20, sometimes less — to a new account without requiring a deposit first. That money is not withdrawable as-is. It carries a wagering requirement, commonly in the 40× to 60× range, and maximum cashout caps that limit what you can take even if you somehow clear the playthrough. Win A$300 from a no-deposit bonus with a A$50 cashout cap and you are permitted to withdraw A$50.
Treat these as a free trial with ungenerous terms, not as money. They let you test the cashier and the lobby’s speed without funding the account, which has some value. The idea that they represent “free money” is marketing, and the reader searching for free-credit PayID pokies is searching for something that does not exist at commercial scale.
Are the “free credit” and no-deposit PayID pokies offers real?
Real in the sense that A$10 or A$20 of site credit is sometimes awarded without a deposit, yes. Withdrawable without a 40× to 60× wagering requirement and a low maximum cashout cap, no. They are time-limited trials, not money you can take.
New Sites, The Games, And Knowing When To Stop
Competitor rankings on this topic vary so wildly from page to page that the variation itself is the story. One site puts Wincrown at number one, another opens with iWild, a third with Ricky Casino, a fourth with SkyCrown. They are ranking different things under the same heading, and what they are ranking is whatever their commercial relationship supports that month.
Newer Sites And Why Tenure Matters Here
Stellar Spins and any other operator that launched in the past year or two carries more counterparty risk than Joe Fortune’s nine years or Ricky Casino’s long Australian track record, for a reason that has nothing to do with the quality of the pokies or the size of the welcome package. When a site is new, its documented payout behaviour is thin. You have no body of independently recorded cashout times, no long public thread of complaints or satisfied reviews, and no operating history to judge it against when something goes wrong.
On a reversible payment rail that is an acceptable trade-off. On an irreversible one, tenure is not a nice-to-have — it is most of what you have to go on when you are choosing where to send money that cannot be called back. Deposit small at new sites, and only increase once the first withdrawal clears.
What You’ll Actually Be Playing
Pragmatic Play and BGaming appear in almost every lobby here. Gates of Olympus, Sweet Bonanza, Big Bass Bonanza and Wolf Gold are the universal titles. Operator differentiation happens at provider count — Lucky7’s 168 studios is the widest selection — and in the RTP filters, which separate the sites that let you sort by return-to-player percentage from the ones that bury it.
High RTP does not mean you will win. It means the house edge is smaller, so your bankroll lasts longer per spin. Big Bass Bonanza at 96.71% returns more over a long run than a 94% title at the same stake. The difference compounds across thousands of spins, which is why serious players check RTP before they check bonus size. Volatility is the other axis: low-volatility pokies pay small amounts frequently, high-volatility ones pay rarely but larger. Match those to your actual goal — a long session or a single big hit — rather than picking on theme.
How This List Was Put Together
The operators here were selected by which names appear most frequently in Australian player search behaviour, cross-referenced against verifiable PayID cashier presence and published payout documentation where available. The order reflects PayID capability specifically — two-way support, tested cashout times, AUD-native accounting, and minimum deposit floor — rather than bonus size, because those are the attributes that matter to the rail.
Every affiliate page ranks the sites that pay them best. This one does too, though payment here is structured as flat editorial fee rather than per-signup commission. The 2026 legislative changes taking effect in January 2027 will reshape that across the industry, and it remains to be seen which pages survive the adjustment. What does not change: if four different pages present four different operators as number one, none of those rankings are measuring site quality. They are measuring commercial arrangements.
Setting Limits And Getting Help
BetStop is the national self-exclusion register for Australian-licensed wagering services. Register at betstop.gov.au and you will be excluded from every licensed bookmaker in the country in a single step. It does not reach offshore pokies sites, because they do not hold Australian licences and are not part of the register’s scope. If you are using BetStop as a control tool, know that gap before you rely on it.
Deposit limits in your banking app are a stronger lever than site-level tools, because the site-level setting can be turned off by the same person who set it. A daily PayID cap enforced by your bank cannot. Set it while you are thinking clearly, not mid-session.
The National Gambling Helpline is 1800 858 858, free and available 24 hours a day. Gambling Help Online offers free confidential chat and email counselling around the clock at gamblinghelponline.org.au. Australian gambling losses across all forms reached A$32.18 billion in the 2023–24 financial year. That figure is not a moral judgment — it is a statement of scale, and the scale is worth understanding when you are deciding how much to risk.
Commercial gambling is designed for the operator to win. Play because the session is entertaining within a budget you set in advance, not because you expect the outcome to be profitable. If you are depositing to recover prior losses, that is the clearest possible signal to stop.
Do you need to verify your identity for a PayID pokies account?
Usually at first withdrawal rather than first deposit. Lucky7 publishes a A$1,000 cumulative threshold below which documents are not requested. Most sites trigger KYC when you request the first cashout, which adds 12 to 48 hours to that withdrawal.
18+. Gamble responsibly. If gambling is no longer fun, it is time to stop.
Deposit Methods at Australian Online Casinos 2026 — Compared
Content created by the «AussieChips» team
